Know How an Underwriter Sees Your Fleet.
Before They Do.
Your public compliance record quietly decides your premium, your deductible and whether a shipper signs. X3 Insurability scores that record the way underwriting reads it — one Fleet Insurability Score from your exposure-normalized CSA BASICs — then ranks the fixes that raise it and routes each one to the X3 product that closes it, before renewal.
You’re Not Buying Insurance. You’re Selling Your Insurability.
Before an underwriter quotes your renewal, they pull the same public record anyone can: your CSA BASIC percentiles, your inspection history, your crashes, your out-of-service rate. Every elevated BASIC becomes a premium, a deductible, a coverage limit — or a shipper that goes with someone else. Most fleets find out what the underwriter saw when the renewal lands, sixty days too late to change any of it.
The underwriter reads your record in ten minutes. You should read it first.
Your Record In. The Underwriter’s View Out.
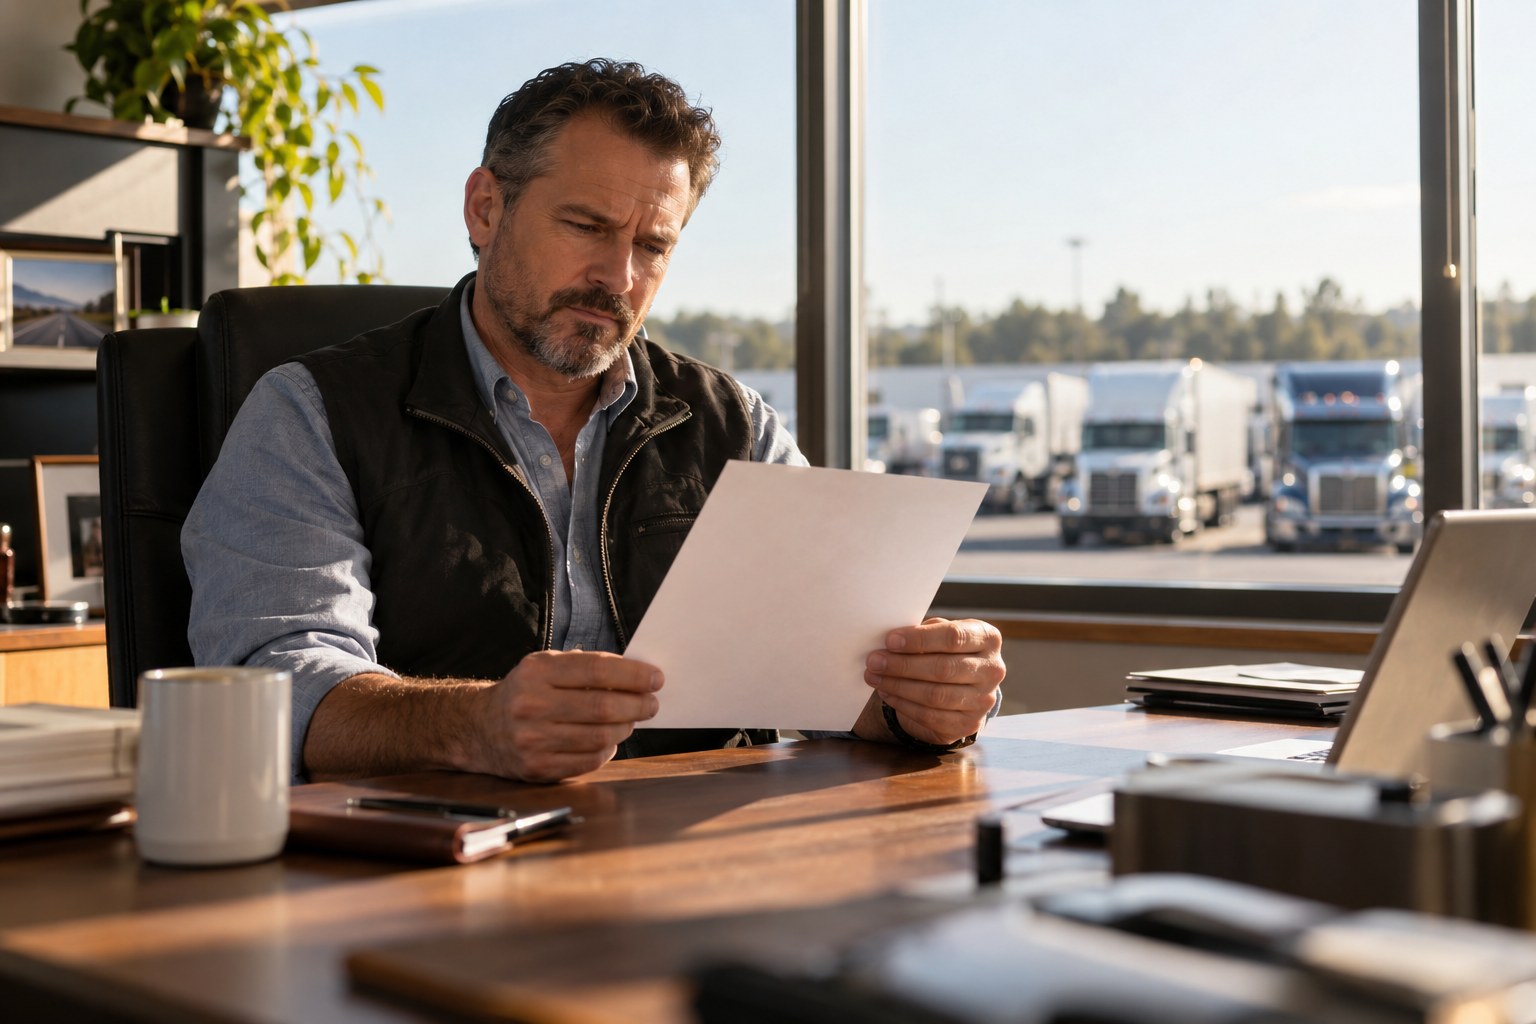
Enter a USDOT number and X3 pulls the carrier’s live public CSA record, scores it from exposure-normalized SMS BASIC percentiles — so a big fleet isn’t punished for raw volume — and returns one Fleet Insurability Score with a risk band, the factors moving it, and how many points each fix recovers.
0–100, banded Preferred / Standard / Substandard / High-risk — the number an owner, an underwriter and a shipper can all read.
Unsafe Driving, HOS, Driver Fitness, Vehicle Maintenance, Controlled Substances, HazMat, Crash — percentile by percentile.
Which issues drag the score, how many points each fix recovers, and which one crosses you into the next band.
Each fix links to the X3 product that performs it — HOS, DataQ, MVR, Drug & Alcohol, HazMat, Preventability.
Crashes and OOS counts are shown for context — the score comes from percentiles, the way underwriting normalizes risk.
Risk loading is a directional model, clearly marked — never a quote, never an underwriting decision.
Stop guessing what the underwriter saw. Start knowing your score.
Enter Your DOT. See What an Underwriter Sees.
Free, no card, no account. X3 pulls the live public record and returns the score, the band and the top factors — the same dashboard your real fleet fills after sign-up.
- Hours-of-Service BASIC elevated — recover 18 points → X3 HOS
- Vehicle Maintenance BASIC elevated — recover 6 points → X3 CSA / DataQ
- Two crash-indicator inspections worth a DataQ review → X3 DataQ
- Renewal in 60 days — enter the policy so the runway is tracked → Renewal Tracker
Every Risk Domain the Underwriter Weighs. In One Number.
Underwriting reads seven BASICs and a crash history. X3 reads the same seven, normalizes each for your exposure, and routes every elevated one to the product that fixes it — so the score isn’t just a diagnosis, it’s a work order.
Seven BASICs. One Score.
Unsafe Driving
Speeding, following, lane — the behavior underwriters weigh first.Crash Indicator
Reportable crash history, DataQ-able where preventability applies.HOS Compliance
Log and ELD violations — the most common premium driver.Vehicle Maintenance
Brakes, tires, lights — OOS rate the underwriter sees.Controlled Substances
Drug and alcohol violations and program gaps.HazMat
Placards, papers and packaging, where applicable.Driver Fitness
Qualification, medical, licensing — the DQ file.The Score Is the Diagnosis. The Fix List Is the Cure.
X3 turns the underwriter’s view into a ranked sequence — the fix, the points it recovers, the band it crosses, and the X3 product that closes it — so you walk into renewal with the record already moving your way.
Enter your DOT
X3 pulls the live public FMCSA record — BASIC percentiles, inspections, crashes, OOS — no spreadsheets, no manual entry.
Get the score and band
One Fleet Insurability Score, exposure-normalized, with the factors and points behind it.
Rank the fixes
Which fix recovers the most points, which one crosses a band, and what the whole list would reach.
Route each fix
Every fix opens the X3 product that performs it — a DataQ challenge, an HOS coaching plan, a DQ file gap.
Track the renewal
Enter your policies, COIs and renewal dates once; X3 warns at 60 days, 30 days and lapse.
Build the packet
An executive risk report and an underwriter-ready evidence packet: the score, the trend, what you fixed and when.
Re-score before you renew
Every check adds to your carrier history, so the story you tell the underwriter is the one the record tells.
Score. Rank. Route. Prove. Then renew.
Walk Into Renewal Ready. Not Surprised.
Insurance data isn’t in FMCSA, so X3 doesn’t pretend to pull it. You enter each policy once — carrier, insurer, coverage limit, renewal date — and X3 tracks the runway: approaching at 60 days, expiring at 30, lapsed the day it happens. Pair it with the score and you know what to fix, and how long you have to fix it.
Policy renewals, COI expirations, MCS-90 and authority filings, and the score itself.
The BASIC that moved, the COI about to expire, the band you’re about to cross — either direction.
To the safety manager, the owner or the broker — with the points at stake and the date.
Every closed fix lands in the evidence packet with its date and its effect on the score.
Your broker shouldn’t be the one who tells you your HOS BASIC is elevated. X3 should have told you in March.
The CEO View of Business Risk.
One view across every carrier you run: the score and band, the BASICs driving it, the points on the table, the renewals coming up and the fixes in flight — the answer to “how insurable are we, and what would change it?”
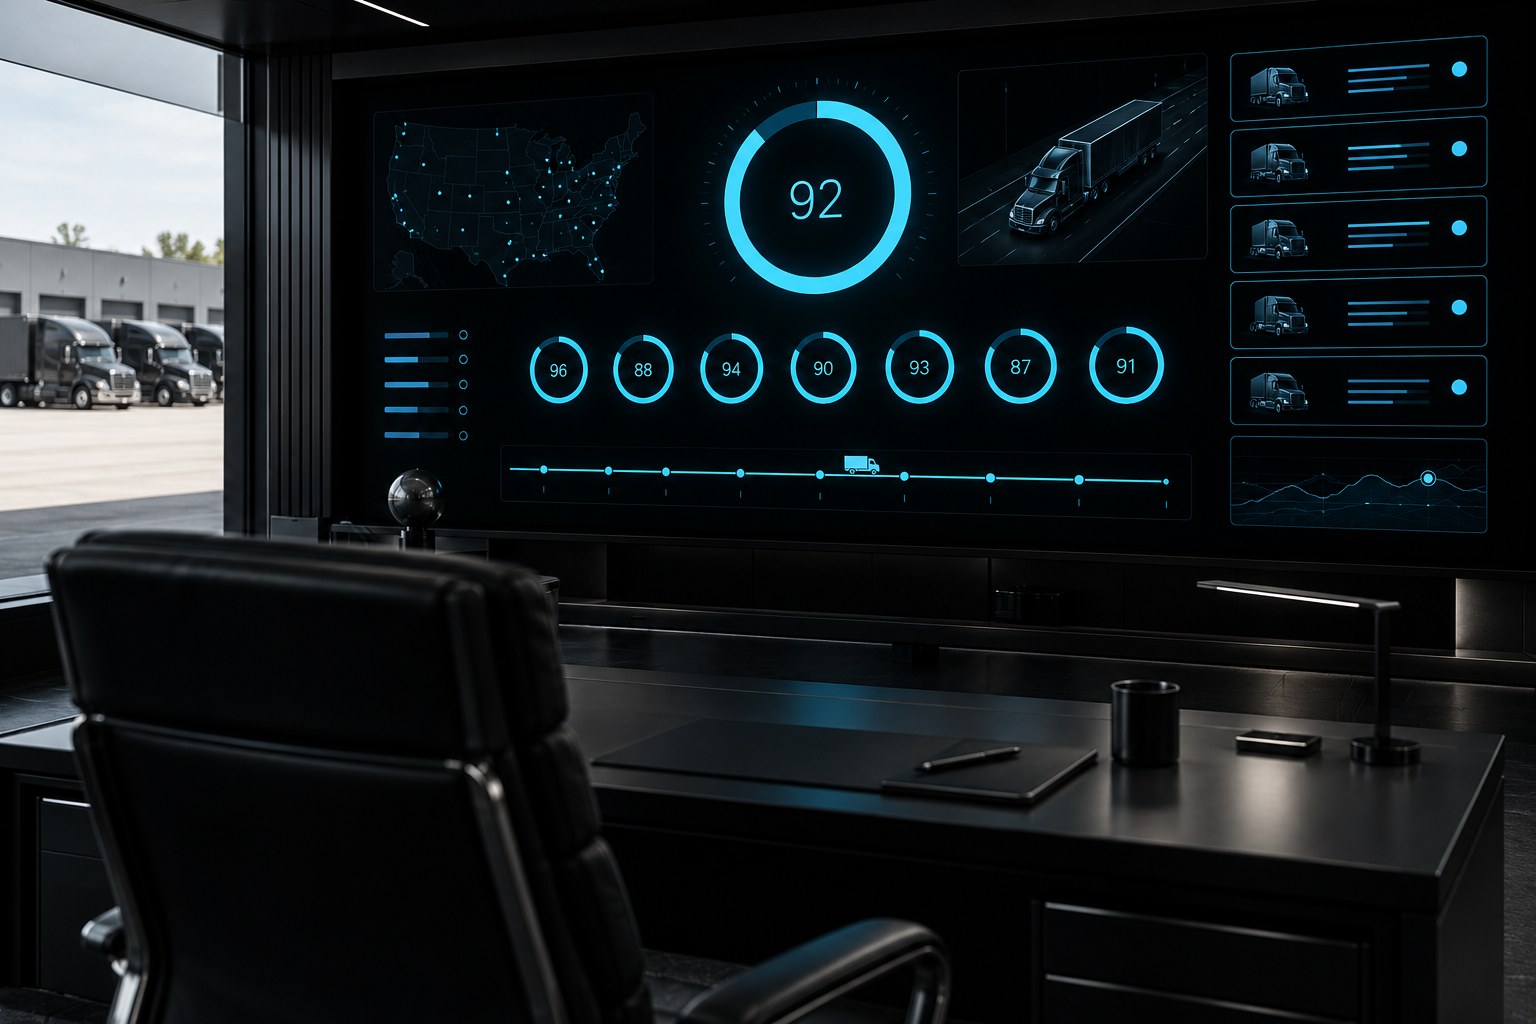
One DOT or twenty. One answer to “how does the underwriter see us?”
The Owner, the Underwriter and the Shipper All Read the Same Number.
The owner asks “how healthy is my business?” The underwriter asks “how risky is this fleet?” The shipper asks “can I trust this carrier?” The Fleet Insurability Score answers all three at once, from the record all three already see — and gives you the fixes before any of them ask.
Walk In With the Story. Not the Surprise.
A renewal at a fleet that knows its score is a packet and a conversation: here’s the record, here’s what we fixed, here’s the trend. At a fleet that doesn’t, it’s a number on a letter and a scramble. X3 Insurability puts you in the first group — and gives the underwriter a reason to price you there.
See the elevated BASIC months before the underwriter does.
Close the fixes with the most points, in the product that performs them.
Hand over the evidence packet with the score, the trend and the dates.
One Plan That Scales With Your Fleet.
Every tool included, every carrier included — and the bigger you get, the less you pay per truck. The instant check stays free.
- ✓Fleet Insurability Score, band & premium-impact fix list
- ✓COI & renewal tracker, MCS-90 and authority monitoring
- ✓Executive Risk Report & underwriter-ready evidence packet
- ✓AI Insurance Advisor & twelve specialist agents
- ✓Unlimited carriers and team seats as you grow
| Up to 10 trucks | $99 |
| 25 trucks | $249 |
| 50 trucks | $499 |
| 100 trucks | $749 |
| 250 trucks | $1,499 |
| 1,000 trucks | $5,249 |
X3 Insurability presents modeled risk indicators built on public compliance data — not an insurance quote, a guaranteed premium, or an underwriting decision. X3 is not an insurer or broker and does not sell, place or quote insurance; verify coverage with your agent and against your official record. Not affiliated with FMCSA or USDOT.
Frequently Asked Questions.
What owners, safety managers and brokers ask before they put X3 over their fleet’s risk.
Is this an insurance quote?
Where does the score come from?
What is “premium impact”?
Will this lower my premium?
Does X3 pull my insurance policies automatically?
Does it work with my other X3 products?
Is the instant check really free?
How often should I re-score?
Does AI replace our broker or safety consultant?
How does pricing work?
You Already Know Your Record. Now Know How It’s Priced.
Enter your DOT and X3 shows you the score, the band, the points on the table and the fixes that move them — free, in seconds.